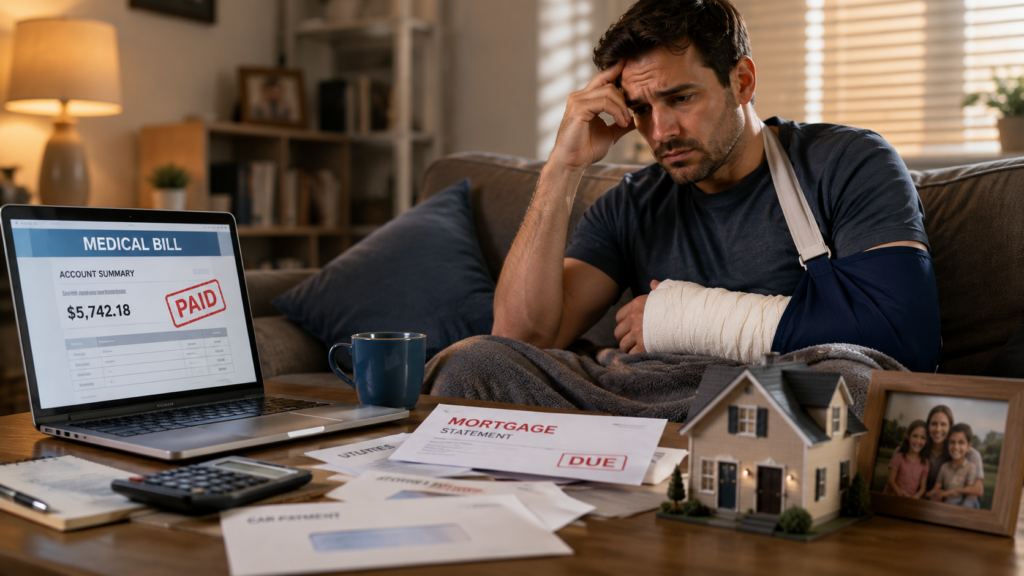
Health insurance may pay the provider—but who helps pay the mortgage while you recover?
Most people understand the importance of health insurance. It can help with covered doctor visits, hospital care, prescriptions, testing and other medical services.
But health insurance is generally designed to help pay eligible healthcare expenses—not replace your paycheck or cover every household bill that continues arriving while you recover.
That distinction often becomes clear only after someone experiences a serious illness, accident or hospitalization.
Medical bills are only part of the financial impact
Imagine being unable to work for several weeks. Even if your health plan covers a large portion of your medical care, your family may still be responsible for:
Deductibles, copayments and coinsurance
Mortgage or rent payments
Groceries and utilities
Childcare
Transportation to appointments
Hotel stays or meals near a treatment facility
Help around the house
Lost wages for the patient or caregiver
The medical event may be temporary, but the financial consequences can last much longer.
“Ihave health insurance” doesn’t always mean “I’m fully protected”
Comprehensive health insurance is an essential part of a financial protection strategy, but it was not designed to cover every expense caused by an illness or injury.
A plan may help pay the hospital, surgeon or other healthcare provider. It typically does not send money to your mortgage company because you missed work.
This is where additional protection may be worth considering.
What types of coverage may help fill the gap?
Different products serve different purposes. Understanding those differences can help you decide whether you have an overlooked vulnerability.
Hospital indemnity insurance
Hospital indemnity insurance may pay fixed cash benefits when a covered hospital event occurs. Depending on the policy, benefits may be based on an admission, hospital stay, intensive-care stay or other covered service.
The cash benefit is generally paid according to the policy’s schedule rather than the size of the hospital bill. It may be used for medical or everyday expenses, such as a deductible, mortgage payment, groceries or transportation.
Critical illness coverage may provide a lump-sum cash benefit after a covered diagnosis, such as certain cancers, heart attacks or strokes.
The money may help with expenses that continue during treatment and recovery. However, covered conditions, definitions, waiting periods and benefit amounts vary by policy.
Accident insurance
Accident insurance may pay scheduled benefits for covered accidental injuries and related services. Depending on the policy, this could include emergency care, imaging, fractures, ambulance transportation, follow-up appointments or physical therapy.
It generally does not cover illnesses or every type of injury.
Disability income insurance
Disability coverage is designed to replace a portion of qualifying lost income when an illness or injury prevents you from working.
Short-term disability may help during a temporary absence, while long-term disability may provide benefits for a more extended qualifying disability. Waiting periods, benefit periods and definitions of disability can vary significantly.
Before buying additional coverage, do the math
Supplemental protection should solve a real financial problem—not simply add another premium to your budget.
Start by asking:
How many months could we pay our bills without my income?
What is our health plan’s deductible and maximum out-of-pocket amount?
Does my employer provide disability coverage?
How much income would that coverage replace?
Would the benefit be taxable?
Do we have savings available for nonmedical expenses?
Which family member’s absence would create the greatest financial strain?
Are there waiting periods, exclusions or preexisting-condition provisions?
The right solution depends on your health coverage, employment benefits, savings, household expenses and budget.
Read the policy—not just the brochure
No supplemental policy covers everything. Before enrolling, review:
Covered events and conditions
Benefit amounts
Waiting or elimination periods
Preexisting-condition provisions
Exclusions and limitations
Age-based reductions
How and when claims must be submitted
Whether benefits are paid once or can be paid more than once
Ask for clarification when something is unclear. A policy’s actual contract—not a marketing summary—determines whether a claim is payable.
Protection is about more than the hospital bill
The purpose of additional coverage is not to insure every inconvenience. It is to reduce the chance that a health event becomes a household financial crisis.
Your medical plan may help protect your access to healthcare. Supplemental cash-benefit or disability coverage may help protect the income and stability you have worked hard to build.
At Kannonball Insurance Solutions, we can help you review what you already have, identify possible gaps and explore available options without assuming that every family needs the same solution.
Sometimes the most important coverage is the coverage you do not realize is missing—until you need it.
Coverage, benefits, exclusions, waiting periods and availability vary by policy and state. Supplemental insurance is not a substitute for comprehensive major medical coverage.